
It’s the perfect storm for household budgets
The repercussions of Trump’s shifting narratives

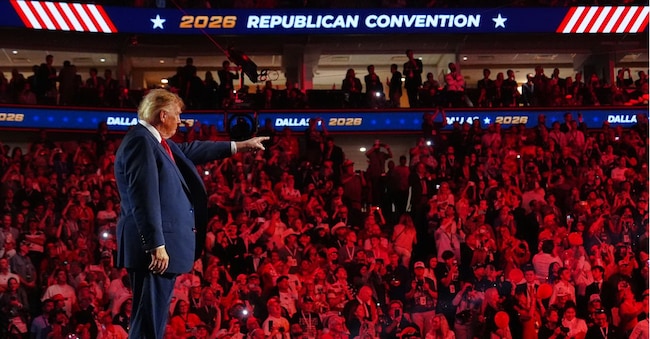
Until a few days ago, Donald Trump was portraying the conflict with Iran as nearing its end – a chapter destined to draw to a swift close within a few days with an American victory and, above all, a collapse in energy prices. This week, speaking from the stage at the Republican convention in Dallas, the US President suggested for the first time that the conflict is not short-lived, but that it will end immediately after the mid-term elections in November.
A shift in the narrative that is not merely political, but also economic, set to strike at the heart of Europe’s energy supply strategies. For months, Europe had been hoping for a happy ending to the US-Iran memorandum of understanding, signed on 17 June, in order to rebuild reserves at lower prices and restore stock levels to adequate levels. But winter is just around the corner and gas storage levels in the EU (66–67 per cent) are at their lowest in 15 years.
We must therefore change our thinking. Energy reserves are the first line of defence against a new energy crisis. Italia is in a better position, with storage levels at 84 per cent. Only 6 per cent is needed to reach at least 90 per cent capacity by 1 November each year, as required by European legislation. All this whilst gas prices exceed 80 euros per MWh and Brent crude breaks the 100-dollar-per-barrel mark, with far more critical scenarios looming in the event of more prolonged supply disruptions.
After years of moderate, largely demand-driven inflation, the European economy is now facing continuous supply-side inflationary shocks, not only from energy but from a number of fronts: rising production costs for fertilisers, food, transport and other raw materials. With inflation running at over 3 per cent, the ECB is forced to continue raising interest rates.
But central banks cannot produce oil, reopen the Strait of Hormuz, repair a refinery or improve a harvest with El Niño looming: their hands are tied when it comes to supply, and they can only influence inflationary dynamics by trying to curb demand. Their main tool remains raising interest rates, but this does not address the root causes of the shock and, what is more, further impacts the household budgets of families already struggling with soaring petrol prices, utility bills and the cost of the weekly shop. Higher borrowing costs mean higher mortgage and loan repayments, reducing households’ ability to spread major expenses over time; but they also mean a slowdown in real incomes, which limits purchasing power and, more generally, curtails spending and saving capacity.


