
A sector accounting for 9 per cent of GDP: all the logistics figures
The sector employs 1.4 million people, has a turnover from contract work of over 120 billion and handles 1,200 million tonnes of goods

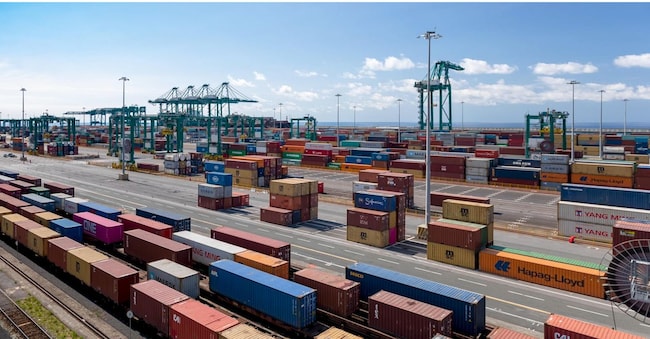
A sector accounting for 9 per cent of Italia’s GDP, which is the third largest in the European Union with a market share of around 10 per cent, employing 1.4 million people and comprising several tens of thousands of businesses, including transport companies, logistics operators and couriers. The Italian logistics system – regarded by some as merely a hidden supply chain, by others as a true driving force of the economy – boasts impressive figures but is not yet at the very highest level of efficiency, given that the World Bank’s performance index ranks it 19th in the world. According to a Contship-SRM Intesa Sanpaolo report, industrial firms regard it as one of the decisive factors for their competitiveness, whilst a recent analysis by Cassa Depositi e Prestiti assesses its multiplier effect on the national economy: for every million invested in the sector, 2.1 million in additional total output is generated.
Companies, vehicle fleet and goods transported
The sector – which various studies estimate comprises around 80–85,000 companies across transport, warehousing and courier services, although the National Register of Road Hauliers alone (according to the 2025 statistics from the official journal TIR) lists over 99,000 active companies – shows a clear imbalance in favour of transport companies compared to service providers, as well as marked fragmentation, with a few large national groups and a multitude of micro and small enterprises. In the road haulage sector, although companies with a maximum of five vehicles account for over half the total, it is the more structured firms with larger fleets that have been growing at a significant rate in recent years: there are nearly 1,100 companies with over 100 vehicles. Road hauliers specialising in the temperature-controlled transport of perishable goods are growing both in number (65,000) and in terms of vehicles (184,000), whilst those authorised to carry dangerous goods remain stable at 6,300, with a fleet of over 50,000 vehicles. In total, the fleet of companies operating on a contract basis exceeds 900,000 vehicles: among lorries alone, 60 per cent are Euro 6-compliant, whilst electric lorries account for less than 1 per cent but are growing rapidly, a sign of the industry’s commitment to modernisation.
In 2024, this entire transport sector carried 1,200 million tonnes of goods, 90 per cent of which was by road (this segment has grown by 30 per cent over the last 10 years) and the remainder by rail. In road transport, Italia accounts for over 8 per cent of the European total, despite having a less developed motorway network than other EU countries, whilst in rail transport it accounts for over 6 per cent, despite having less infrastructure than Germany and Poland. In terms of volumes, contract transport is by far the dominant mode, particularly as delivery distances increase.
The challenges: from intermodal transport to consolidation
And what about the challenges of the future? According to Contship-SRM, these are, first and foremost, intermodality – which is still underutilised by both manufacturers and logistics operators – and digitalisation, for which 6 out of 10 companies will increase their investment over the next five years. AI solutions are still the preserve of a very few. Another trend is that of competitive consolidation, which is seeing the more well-structured companies grow and the number of mergers increase.
Economic uncertainty and contracts
In the immediate term, there is also a need – given the heightened uncertainties in the economic climate – to regulate the relationship between the client and the provider of logistics or transport services in a more precise manner. According to the Contract Logistics Observatory at the Politecnico di Milano, today’s contracts make much greater use of indexation to protect against various cost variables (fuel, ISTAT adjustments, labour costs, ETS, energy costs) and contracts are updated more frequently. However, risk management clauses are also changing, and there is a demand for structured collaboration to find shared solutions within a rapidly changing landscape.


