Taxation and employment

America’s Cup: two-year exemption from IRES and IRAP for all competing teams

To qualify for the benefit, you must keep separate accounts

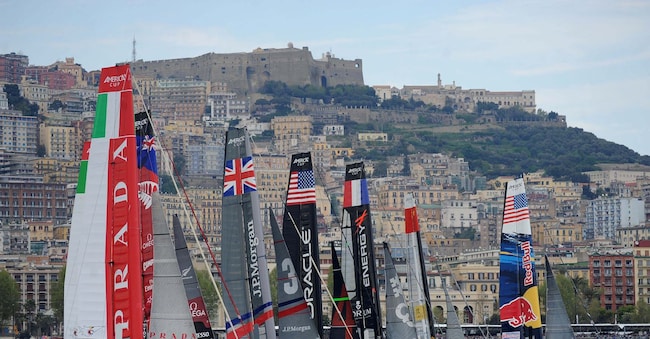
Foto IPP/Felice De Martino 
Napoli 20/04/2013 
Vela 
34a America's Cup World Series Semifinali 
Nella foto: Match Racing Championship IPP

3' min read

Translated by AI
Versione italiana

3' min read

Translated by AI
Versione italiana

Legal entities with their registered office in Italia, established by the organising body or by the participating teams in the America’s Cup Napoli 2027, will be eligible for a range of tax and employment law concessions.

IRES and IRAP relief

Firstly, these entities will be eligible for the IRES and IRAP exemption in respect of activities carried out in accordance with their institutional purposes during the period from 1 January 2026 to 31 December 2027. The tax relief in question, introduced by Article 8 of Decree-Law No 38 of 27 March 2026, was subsequently amended by Decree-Law No 108 of 26 June 2026.

Loading...

The condition for qualifying for the tax relief is, in fact, the establishment of a specific separate set of accounts in which all income and expenditure items directly and exclusively related to participation in the sporting event are recorded. The tax relief in question also applies, under the same conditions, to permanent establishments set up in Italia for the duration of the event by the organising body or by the participating teams.

VAT refunds

Under Article 3 of Decree-Law No 108 of 26 June 2026, the scope was extended the right to a refund of value added tax, as provided for in Article 38-bis2 of Presidential Decree 633/1972, to entities established in third countries without a permanent establishment in Italia, thereby removing the requirement of reciprocity (i.e. the condition that the country of establishment grants similar treatment to Italian operators).

For the 2027 America’s Cup, however, the legislator has introduced an explicit exemption, justified on the grounds of the public interest associated with the staging of the event. The waiver of the reciprocity requirement applies exclusively to VAT paid on purchases and imports of goods and services made within Italy and directly necessary for the conduct of activities related to the event.

Labour law and regulations

Article 4 of Decree-Law No. 108 of 26 June 2026 introduced exceptional provisions regarding fixed-term employment contracts, designed to facilitate the management of the event’s organisational requirements. The new rules apply to employment relationships established by the organising body and the participating teams for the preparation, conduct and conclusion of the event, until such time as these activities are completed and, in any event, no later than 31 December 2027. The provision in question expressly classifies the requirements related to the event as an ‘objective reason’ sufficient to justify the inclusion of a fixed term in employment contracts, thereby allowing a significant derogation from the ordinary provisions of Legislative Decree 81/2015.

In particular, the restrictions relating to the total duration of the employment relationship, extensions, renewals and the quantitative limits normally applicable to fixed-term contracts and agency work can be overcome. However, certain safeguards remain in place. The employment relationship with the same worker may not exceed a total of 24 months nor continue beyond 31 December 2027. Furthermore, the number of renewals may not exceed six. Exceeding these limits will result in the application of the consequences normally provided for in Article 28 of Legislative Decree 81/2015, including the conversion of the contract into a permanent one. For sports workers, however, the special provisions contained in Legislative Decree 36/2021 continue to apply, including the fixed-term contract regime where this is more favourable.

Stamp duty exemption

The allocation and temporary use of the radio frequencies required for the races will be free of charge, and all documentation relating to these authorisation measures is exempt from stamp duty (Article 3 of Decree-Law 108/2026).

Copyright reserved ©
Loading...

Brand connect

Loading...

Newsletter

Notizie e approfondimenti sugli avvenimenti politici, economici e finanziari.

Iscriviti