
Fincantieri slips along with defence shares, but its results are welcomed by analysts
It reported a rise in profits and revised its guidance for 2026 (adjusted EBITDA now forecast at €715–725 million, up from the previous €700–710 million). Avio and Leonardo are also among the top performers on the FTSE MIB

Le ultime da Radiocor
*** Ucraina: Zelensky, "Usa propongono cessione Donbass in cambio adesione Nato"
Cina: giovedi' incontro tra Trump, Xi e Putin a Shenzhen
Usa: migliaia viaggiatori a terra per problemi a sistemi tlc, ancora disagi oggi
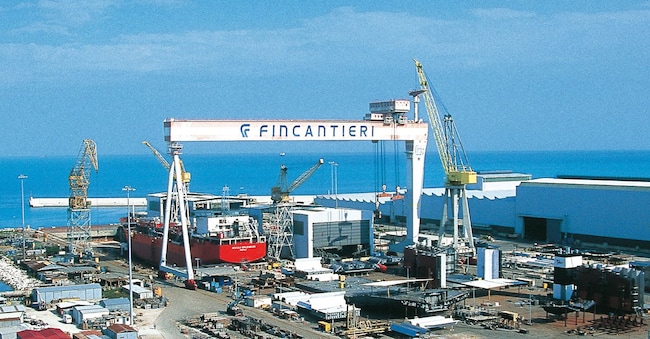
(Il Sole 24 Ore Radiocor) - A session in the red for Fincantieri , one of the worst performers on the FTSE MIB index, with a fall of nearly four points. Although the results, published the day before, showed a rise in profit and an upward revision to guidance for 2026 (adjusted EBITDA forecast at €715–725 million, up from the previous €700–710 million) and were generally well received by analysts, the share price was held back by the performance of the defence sector, which is falling across Europe, with the Stoxx Europe Targeted Defence index down by 1.44 per cent. In fact, on the Milan Stock Exchange, Avio (down by more than three points) and Leonardo (down by over one point) on the Milan Stock Exchange; the latter was further penalised by the fact that Morgan Stanley has lowered its target price to 77 euros from 82 euros. In London, BAE Systems is down by around 1 per cent; Thales in Paris is down by 0.7 per cent; and in Frankfurt, Rheinmetall is down by 0.8 per cent.
Turning back to Fincantieri, the performance over the first nine months confirms the acceleration in the group’s profitability, underpinned by structural demand in its key markets and increasingly solid industrial and financial fundamentals. “The total order book stands at €72.6 billion, almost eight times last year’s revenue, ensuring us long-term industrial visibility, which is unique in the sector,” said CEO Pierroberto Folgiero. The shipbuilding group reported an EBITDA of €511 million, up 10.9 per cent, on revenues down 1.8 per cent to €6.6 billion.
The profit margin has risen to 7.7 per cent from 6.9 per cent a year ago, and the group now expects full-year EBITDA to reach the range of 715–725 million, compared with the 700–710 million previously estimated. New orders secured in the first nine months totalled 9.7 billion (16 billion a year ago) and bring the total order book to a record 44.7 billion (+8.8% compared with the end of 2025). A total of 19 ships have been delivered, and there are 90 in the order book, “with visibility on scheduled deliveries up to 2036”.
The third-quarter results “confirm the trend towards improved margins” and are “in line at an operational level (and largely at a divisional level as well) whilst free cash flow and order intake have improved; the latter, in the third quarter, includes the significant military order for two Ddx vessels for the Italian Navy, with a contribution from 2027”, explain analysts at Equita, which has raised its target price to €16.2. Intermonte, which has confirmed its “outperform” rating whilst raising its target price from €18.2 to €18.5, believes that the results have “strengthened the investment case, confirming a structural improvement in profitability, underpinned by the Cruise division thanks to pricing, standardisation of orders and industrial efficiencies, despite the persistent weakness in Naval revenues. The conversion of the Defence pipeline is becoming increasingly concrete, with Ddx set to contribute from 2027, US LSM negotiations in their final stages and the formalisation of the Portuguese FREMM Evo contract expected shortly”.
Looking ahead, the view is that Fincantieri “is well positioned to accelerate earnings growth over the coming years (2025–2030 CAGR forecast at 32 per cent), thanks to a combination of further margin expansion in the cruise sector and an improved mix driven by the acceleration of the naval and underwater business. “Current valuations are, in our view, attractive,” add the experts at Equita.


