Pharmaceuticals

Recordati: Palliser Capital writes to the board urging it to reject the CVC-GBL takeover bid

The British fund does not consider the price of 51.29 euros per share in the bid launched on 31 August to be fair, a bid which is expected to lead to the company’s delisting

5' min read

Translated by AI
Versione italiana

5' min read

Translated by AI
Versione italiana

The takeover bid for Recordati, which began on 31 August, could face a bumpy ride due to the discontent of some shareholders regarding the price offered, which stands at €51.29 per share . Palliser Capital has come out openly against the deal; in a letter addressed to the board, it raises the issue of the valuation of the shares in the transaction, as well as the terms of the offer. The fund is calling on the board of directors to ‘withdraw its support for the offer and to act responsibly by taking all available measures to protect minority shareholders, including asking the offeror to grant Recordati shareholders a fair and appropriate consideration of at least €60 per share , by increasing the offer price’.

The board of the Italian company had issued a favourable opinion by a majority (six out of ten) on 16 July. The four independent directors (Diva Moriani, Joanna Le Couilliard, Piergiorgio Peluso and Stephen Sands) voted against the resolution; in light of the fairness opinion issued by Rothschild & Co Italia, they had deemed the offer price to be inadequate. On that occasion, Respighi BidCo, the special purpose vehicle jointly controlled by CVC Capital Partners (Fund IX) and Groupe Bruxelles Lambert (GBL) which launched the takeover bid, had made it clear that the terms and conditions ‘remain unchanged’, thereby closing the door on any possibility of a revised bid. The price of 51.29 euros, for a transaction valued at €10.7 billion, incorporates a premium of 12.89 per cent compared with the price on 25 March 2026 – €46.06 per share – the date on which the funds announced their non-binding expression of interest.

Loading...

Now the London-based fund is raising the issue of the price once again – and more besides: ‘The Offer is nothing more than a profoundly unfair and highly irregular transaction, designed to force Recordati’s minority shareholders to sell their shares at a severely disadvantageous price,’ reads the statement from Palliser Capital, which continues: “A transaction structured with the approval of non-independent directors characterised by profound conflicts of interest and a personal stake in the success of the transaction, and pursued despite the unanimous and unreserved opposition of all the independent directors on the board.”

On the Milan Stock Exchange today, the share price stands at 52.55 euros per share, above the takeover bid price, with a rise of less than half a percentage point by mid-morning.

Acceptances of the takeover bid

As part of the voluntary full takeover bid launched by Respighi BidCo (a vehicle of CVC and GBL) for Recordati’s ordinary shares, it appears that 3,840 applications were submitted today, 14 September. Consequently, the total number of acceptance requests now stands at 98,278,175, representing approximately 49.50% of the total securities subject to the offer.
This stake includes the 46.82 per cent holding held by Rossini S.à r.l., an investment company through which the CVC Capital Partners fund holds a majority stake and controls Recordati; the stake held by Andrea Recordati, chairman of Recordati, who accepted the takeover bid by selling 200,000 ordinary shares with a total value of €10.26 million; the stake held by Arisca S.r.l., a company closely linked to Andrea Recordati, which accepted the offer by selling 122,903 ordinary shares with a total value of 6.31 million euros; the stake held by Recordati’s CEO Rob Koremans, comprising 78,426 shares with a value of over €4 million.

The fairness opinion from Rothschild & Co Italia

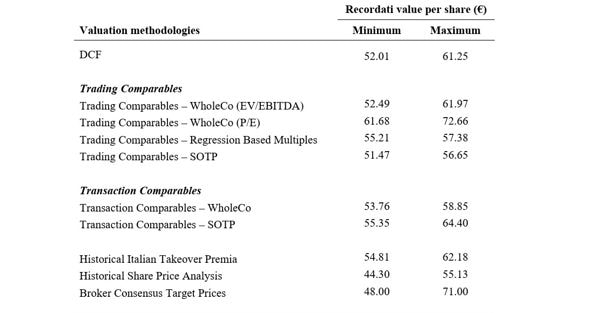
Rothschild & Co, appointed by Recordati’s independent directors, has rejected the price of 51.29 euros per share offered by Respighi BidCo on financial grounds. The fairness opinion, dated 14 July 2026, concludes that the offer price is ‘inadequate from a financial perspective’. This assessment is particularly significant because it is not based on a single methodology, but on a comparison of six different valuation approaches: the discounted cash flow (DCF) method, multiples of comparable listed companies, comparable transactions, premiums historically recognised in Italian takeover bids, the share’s historical performance and analysts’ target prices. The price of €51.29 falls below the figures obtained by most of the methodologies used by Rothschild, whose analysis was also based on Recordati’s 2025–2029 business plan and on information received from management between April and July 2026.

Il valore delle azioni di Recordati

Valutazione di Rotschild & Co Italia risultante dall’applicazione di ciascuna delle metodologie usate

Rothschild & Co

“In light of the considerations set out above, and subject to the provisions set out therein, Rothschild & Co considers that, as at the Reference Date, the Consideration is not financially fair,” concludes the investment bank.

Specifically, the discounted cash flow (DCF) analysis took into account Recordati’s business plan up to 2029 and projected the results beyond that horizon, extending to 2034. Rothschild also singled out Isturisa, a medicine used to treat Cushing’s syndrome, and valued it separately over a time horizon extending to 2040 using a sum-of-the-parts approach.

For the Recordati business, excluding Isturisa, Rothschild used a weighted average cost of capital (WACC) of between 7.8 per cent and 8.3 per cent and a perpetual growth rate of between 1.75 per cent and 2.25 per cent. From 2030 onwards, it has also normalised maintenance capital expenditure at around €100 million per year, adopting, on the whole, more conservative growth assumptions than those based on historical trends and management projections. Finally, Rothschild assumes that, following the loss of exclusivity, revenue will fall by between 65 per cent and 80 per cent. Even using this relatively conservative assumption, the DCF analysis yields a value of between €52.01 and €61.25 per share, with the lower limit already exceeding the €51.29 offered in the takeover bid.

Loading...

Lazard’s fairness opinion

Lazard’s fairness opinion, commissioned by the board, reaches the opposite conclusion to that of Rothschild: Lazard considers the price of 51.29 euros per share to be appropriate from a financial perspective. The French investment bank cited the DCF (Discounted Cash Flow) method as its primary valuation approach. It assessed Recordati’s unlevered, after-tax cash flows from 30 June 2026 to 31 December 2040, using a perpetual growth rate of 0.25%–0.75% and discount rates/WACC of 7.70 per cent–8.70 per cent. The DCF model yields a value per share of €44.98–€54.21. The takeover bid price therefore falls within this range, close to the upper end of the interval.

Lazard also analysed the share’s performance. In the 52 weeks leading up to 9 July 2026, Recordati’s share price had fluctuated between approximately 44.48 and 54.60 euros. As at 25 March 2026, a date considered “undisturbed”, the spot price was €46.06, whilst the weighted average prices were €46.35 over one month, €48.80 over six months and €50.35 over twelve months.

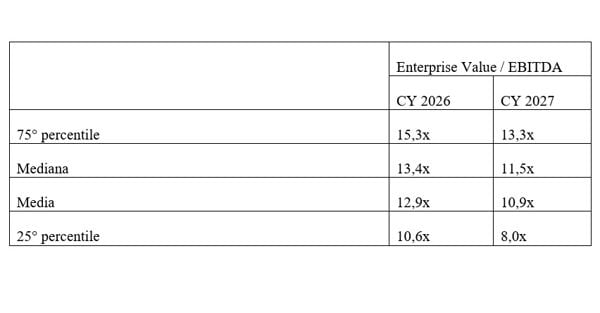
Lazard also examined selected listed companies operating in the biopharmaceutical sector (BioMarin, Ipsen, Orion, Sobi and UCB), analysing their enterprise value expressed as a multiple of the expected revenue and EBITDA of each comparable company, projected for each of the financial years ending 31 December 2026 and 31 December 2027.

Fairness opinion di Lazard

Confronto con società comparable del settore

Lazard

‘On the basis of the foregoing,’ the document states, ‘Lazard has applied EBITDA multiples of +/- 1.0x relative to the median EV/ adjusted EBITDA for CY2026 of the main comparables (core peers), corresponding to 12.4x–14.4x, to the company’s estimated EBITDA for CY2026, in order to calculate an implied value range per share, in each case using the company’s estimated EBITDA as set out in its forecasts. The results of these analyses indicated an implied value per share of between €51.44 and €61.41’.

On the other hand, based on an analysis of previous transactions, Lazard applied ‘EBITDA multiples of +/- 1.0x relative to the median Adjusted LTM EV/EBITDA multiple of comparable transactions, which stood at 12.6x (ranging from 11.6x to 13.6x), to the company’s LTM adjusted EBITDA as at June 2026. The results of the analysis indicated an implied value per share of between €46.71 and €56.55’.

Finally, Lazard examined the historical performance of the share price (and trading volumes) over the 52-week period ending 9 July 2026. During that period, the intraday trading price of the share fluctuated between approximately €44.48 and €54.60 per share. Based on the analysis contained in the document, the investment bank declared the offer price to be fair.

Copyright reserved ©
Loading...

Brand connect

Loading...

Newsletter

Notizie e approfondimenti sugli avvenimenti politici, economici e finanziari.

Iscriviti