
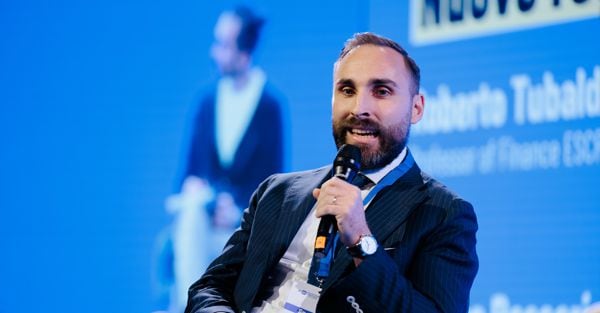
Roberto Tubaldi, ESCP Business School: “Resilient governance of global supply chains helps to safeguard competitiveness”
In complex times such as these, amidst geopolitical tensions and conflicts such as those in the Middle East and Ukraine, according to Roberto Tubaldi, Assistant Professor of Finance at ESCP Business School’s Turin campus, a ‘more diversified, more transparent’ supply chain is essential for ‘reducing the volatility of input costs and the likelihood of rationing during periods of stress’

(Il Sole 24 Ore Radiocor) - Supply chains have taken on an increasingly central role in recent years. Indeed, ‘globalisation has enabled the creation of long, specialised value chains capable of reducing costs and sustaining higher margins’. However, the conflicts in the Middle East and Ukraine, geopolitical tensions and the Covid-19 pandemic “have highlighted the hidden costs of these structures” and the need to take action to improve and strengthen them. This is explained in an interview with Radiocor by Roberto Tubaldi, Assistant Professor of Finance at ESCP Business School on the Turin campus, who argues that a ‘more resilient, more diversified, more transparent’ supply chain is essential for ‘reducing the variability of input costs and the likelihood of rationing during periods of stress’.
Furthermore, shocks in supply chains have a significant impact on the industrial structure, as illustrated by the research Supply Chain Shortages, Large Firms’ Market Power, and Inflation – on which Tubaldi is collaborating with Francesco Franzoni of USI Lugano and the Swiss Finance Institute, and Mariassunta Giannetti of the Stockholm School of Economics. Suffice it to say that, following a supply chain shortage in 2021, larger firms gained a competitive advantage thanks to their diversified supplier networks and greater bargaining power. And the effects are long-lasting: the market share gains made by firms that manage to continue serving their customers during periods of scarcity are largely permanent, whilst pressure on margins eases once supply returns to normal – explains the expert. A robust supply chain therefore protects not only short-term financial results but also long-term competitive position.
Supply chains at the heart of governance
However, disruptions to the supply chain do not merely have operational implications. “Decisions regarding supply chain configuration — vertical integration, diversification of sources, and the level of strategic stock — profoundly alter exposure to operational risk and, consequently, the cost of capital and enterprise value,” explains Tubaldi. Therefore, they should be assessed by boards of directors with ‘the same rigour as that applied to investments in fixed assets’. Added to this is regulatory pressure. ‘The European Corporate Sustainability Reporting Directive (2022) introduces the principle of double materiality, which obliges large companies to report not only on their own environmental and social impacts, but also on how vulnerabilities in the supply chain create measurable financial risks for the company itself’, states the Professor.
Furthermore, supply chain governance is not merely a reputational issue, but a genuine fiduciary obligation. In fact, “institutional investors increasingly view a company’s ability to manage its supply chain as a direct indicator of the quality of its risk management, with implications for the required premium and the cost of capital”, states Tubaldi. Redundancy and diversification are no longer inefficiencies to be minimised, but recognised components of corporate value.
Disruptions create asymmetries
To fully understand the importance of supply chains and any potential issues, however, we need to take a step back and look at the most critical moments – and the imbalances – that disruptions create within the market. ‘When a supplier is unable to meet the full demand, they must necessarily decide whom to serve and whom to ration,’ explains Tubaldi. ‘The logic behind this decision is not random.’ As revealed by the study conducted by the Professor with his colleagues Franzoni and Giannetti – an analysis based on millions of sea shipments to US customers and on the mapping of customer-supplier relationships in over seventy countries – during periods of scarcity, suppliers systematically prioritise the customers who account for the largest share of their revenue. These are not necessarily the largest ‘in absolute terms’, the expert emphasises, but those with a greater relative weight within the supplier’s customer portfolio.


