
Tenaris rewarded following better-than-expected results and positive guidance
In the third quarter, the group saw its profit rise by 15 per cent to $521 million. Since the start of the year, its share price has already risen by almost 55 per cent

Le ultime da Radiocor
Petrolio: torna a salire con Brent sopra 95 $, gas azzera perdite
***Aerei: tre allarmi bomba su voli europei, Dublino-Roma atterra in Francia
Bper: Papa, non ci siamo ancora seduti al tavolo con Unipol su deal Mps
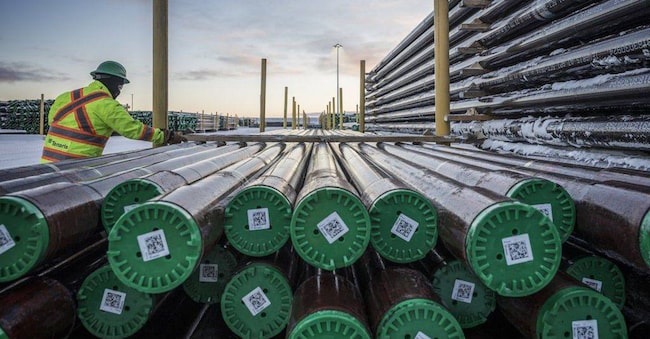
(Il Sole 24 Ore Radiocor) Tenaris is surging on the Milan Stock Exchange, boasting one of the best performances on the FTSE MIB. This is driven by third-quarter results that exceeded market expectations, thanks to higher volumes and margins, and positive guidance, which points to a further improvement in the fourth quarter, for which the company expects ‘an increase in turnover and EBITDA, thanks to stronger demand and rising prices for OCTG (oil country tubular goods, the pipes used in the oil and gas sector for drilling) in North America, as well as an increase in shipments to offshore projects’”.
Profit up 15 per cent in the third quarter
More specifically, in the third quarter, the global manufacturer and supplier of pipes and services for oil and gas exploration and production saw its profit rise by 15 per cent to $521 million (against estimates of $407 million) and revenue rose by 4 per cent to $3.102 billion (exceeding the expected $2.972 billion), thanks to stronger demand in North America and increased shipments to customers in the Middle East. The EBITDA margin stood at 24.4%, up from 23.7% in the same period last year, an improvement even on the 21.9% recorded in the second quarter and, above all, better than the 21.9% expected by the consensus, despite rising costs for raw materials, energy and logistics, and thanks to a favourable product mix and efficient industrial performance, as well as the postponement of maintenance programmes at some plants.
Analysts are pleased with the figures and are already looking ahead to 2027
The third-quarter results “were significantly better than expected, and the outlook for the fourth quarter is also positive, implying further sequential growth in sales and EBITDA and, above all, establishing this quarter as a new baseline looking ahead to 2027”, emphasise the experts at Intermonte. The share price is therefore consolidating the gains recorded so far in 2026 (+54.7 per cent) and over the past year (+47.1 per cent), supported in part by the upward trend in oil prices. “The EBITDA margin came in significantly higher than expected, with a quarter-on-quarter improvement of 250 basis points, compared with the flat figure anticipated, thanks to a favourable product mix, greater operational efficiencies and the postponement of certain plant maintenance programmes, which more than offset the rise in the costs of raw materials, energy and logistics costs”, comment analysts at Equita, who estimate “an EBITDA for the fourth quarter in the region of 830–850 million dollars, which would imply an upward revision of around +7 per cent to the 2026 consensus EBITDA of 3 billion”. Annualising this figure, the experts add, “we would arrive at an EBITDA for 2027 in the region of 34 billion (compared with a consensus of 3.21 billion), with further potential for an upward revision given the favourable trend in Pipe Logix (+8 per cent sequentially in the third quarter and +6 per cent month-on-month in October)’. Overall, the experts at Banca Akros, who confirm their ‘accumulate’ rating and target price of 26 euros, describe the results as ‘good and solid, significantly above expectations, with profit 19 per cent above estimates’.


