Cars and corporate mobility

The drive for efficiency is pushing operators towards consolidation

Mergers and acquisitions reduce costs, whilst new players seek a foothold amongst private individuals and self-employed traders

by Pier Luigi del Viscovo

Aggiungi Il Sole 24 Ore
ai preferiti su Google
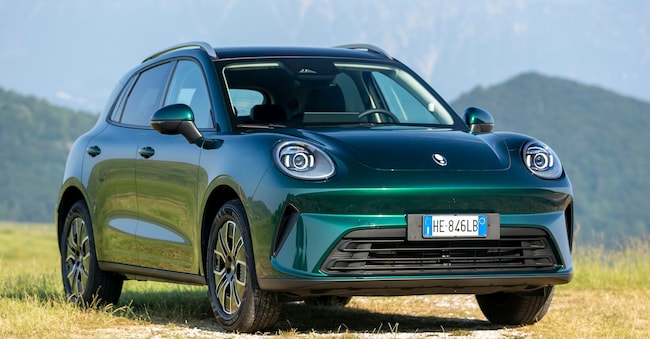
GWM. Ora 5 è il suv prodotto da Great Wall Motor lungo circa 4,5 metri abbinato a motorizzazioni tradizionali, ibride o elettriche e con oltre 400 km di autonomia

4' min read

Translated by AI
Versione italiana

4' min read

Translated by AI
Versione italiana

The long-term hire (NLT) sector is becoming increasingly concentrated, and the more it concentrates, the more new operators enter the market. It’s strange, but that’s how it is. In recent years, Ald/Société Générale bought LeasePlan to merge and form Ayvens; another major player, Unipol (formerly Car Server), has grown by taking over SiFà, whilst Arval acquired Athlon. Well, in every sector there are mergers when demand slows down and stagnates, to generate efficiencies through economies of scale in anticipation of fierce competition on costs and prices, should demand wane. So, what’s the point? The point is that the NLT sector isn’t stagnating – it’s growing. In fact, it has a pool of potential new customers ahead of it who could become actual customers, sooner or later – though this depends very much on what’s on offer.

So, demand is rising but operators are consolidating: why? Firstly, it is worth noting that competition in the NLT sector has always centred on price. One industry leader argues that car hire rates have remained virtually unchanged over the last ten years, whilst car prices have risen by more than half. Let’s see what emerges from an analysis of data from Aniasa, the car hire association.

Loading...

In 2016, the long-term hire sector generated a turnover of 4.3 billion euros from a fleet of 674,000 vehicles, equating to a unit turnover of 697 euros per month. That year, the average net value of cars purchased by the long-term hire sector was €21,439, according to the ‘Mercato a Valore’ analysis by the Fleet&Mobility Research Centre.

Ten years later, in 2025, turnover stood at 9.3 billion for a fleet of 1,320,000 vehicles, with a unit turnover of 587 euros per month. Last year, the net value of NLT’s registered cars was €33,234.

Now, it is true that the net value also takes into account the mix and not just the price, and that the number of new registrations in a given year does not correspond to the number of cars hired during that year.

However, it is very difficult to ignore the powerful message conveyed by these figures: NLT has squeezed costs as far as possible, despite demand having doubled over the past ten years. It is therefore reasonable to conclude that the drive for efficiency is not driven by a shrinking market but forms part of this industry’s competitive strategy, which is geared towards stimulating demand through ever-lower prices.

It is even more reasonable to conclude that this approach has gone down well with customers – or at least with fleet operators, who, together with the public sector, still account for over 85 per cent of turnover. The question is whether it appeals to others as well – those individual customers, with or without a VAT number, who currently account for around 13–14 per cent of turnover (as they have done for far too many years) and whose numbers could increase significantly if given the right incentives.

It is precisely these areas that other car hire companies – whether newly established or relaunching to ensure they are ready – are focusing on. This is the case with Agos Rent and, to some extent, Santander Renting – both subsidiaries of two banking giants – as well as ItalRent, a subsidiary of a leading car distribution group, and Mobilize, which, whilst not a start-up, is nevertheless determined, under its new management, to offer the Renault network the right product for its customers.

In conclusion, the concentration and proliferation of operators are not a contradiction. Rather, they represent the supply side’s response to two very different segments of demand. One segment is solely focused on the monthly payment. You can offer them the best service in the world and even let them experience it first-hand, but when faced with a subscription fee that is ten euros cheaper, they won’t think twice. The other segment, perhaps, is prepared to prioritise other aspects of the service.

Yes, scepticism is only to be expected, given that, despite all the promises, we have yet to see a product that is genuinely different and truly effective for these customers, offering the services they want, the way they want them and when they want them. Perhaps it does exist but they’re not saying so: marketing in Italia is almost never comparative.

Loading...

Finally, we must also consider the barriers to exit for these two customer segments. Although they are faced with a service that leaves a lot to be desired, fleets do not really have many alternatives if they do not want to revert to mileage allowances for employees’ own cars.

The little ones, on the other hand, certainly do: getting out of an NLT and going back to a finance deal takes no time at all – after all, it’s still just a monthly payment.

Copyright reserved ©
Loading...

Brand connect

Loading...

Newsletter

Notizie e approfondimenti sugli avvenimenti politici, economici e finanziari.

Iscriviti