
Tips – from hotel porters to waiters – must be taxed, according to the Court of Cassation
A 5 per cent rate applies both to the generous tips left by guests at exclusive establishments and to the modest tips given by patrons of the corner café

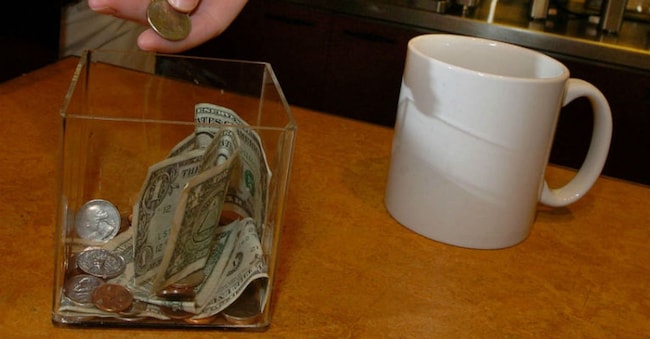
Tips to be taxed for everyone, from the bar waiter to the hotel porter. On this point, the Court of Cassation has not changed its stance, as the appellant had hoped. In fact, the case has been taken up again, reaching the highest court, the doorman of a luxury five-star resort on the Costa Smeralda – the very same resort where the ‘head of reception’ worked, whose appeals the Supreme Court had rejected in judgment 26510/2021.
A dispute relating, then as now, to various tax assessment notices. The tax authorities have set their sights on generous tips, quantified at the time at around 84,000 euros, the result of generous donations from the wealthy guests of the Sardinian ‘dolce vita’ hotel. The defence argument put forward by the current concierge has been rejected; according to him, taxation should apply only to ‘sums paid by the employer as a generous payment, serving as remuneration and within the context of the employment relationship’.
The certainty of a tip
Tips, on the other hand, ‘are collected directly by third parties, with no connection to the employer, who does not determine, collect or interfere with the amounts’. But once again, the judges of the Court of Cassation have refuted this argument and upheld the claims of the Tax Authorities. The Tax Chamber reiterates, in fact, that ‘gratuities of any kind received by an employee in connection with their work, including tips, fall within the all-encompassing concept of income’. And as such, they are therefore taxable.
Generous tips and meagre tips
The Court of Cassation specifically refers to the 2021 ruling concerning the ‘reception desk’ at the very same hotel where the appellant was employed, the grounds for which highlighted that the ‘all-encompassing nature of the concept of income from employment justifies the full taxability of everything the employee receives, even, therefore, as in the case in question, not directly from the employer, but on the receipt of which the employee can, based on common experience, reasonably, if not certainly, rely’.
A principle that applies to everyone working in the tourism and catering sectors, with no distinction between the “generous tips” left by customers at exclusive establishments – as is customary in luxury venues – and the “modest” tips given by patrons of the local corner bar. For everyone, the reduced rate of 5 per cent applies.

