
MPS: shareholder Tortora open to Intesa Sanpaolo’s OPAS
The MPS shareholder via PLT Holding (a long-standing supporter of MPS CEO Luigi Lovaglio): “If there is a need to join, we will join”

Key points
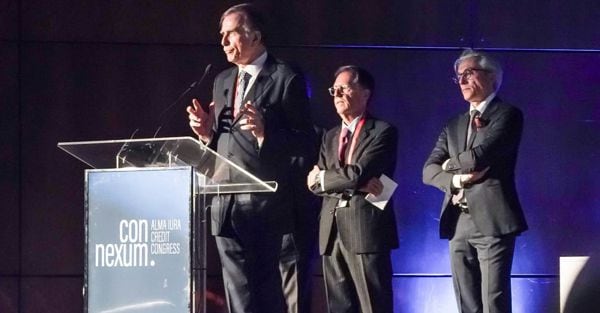
Intesa Sanpaolo’s public offer for MPS is finding new support amongst MPS shareholders. Pierluigi Tortora, a shareholder in the Tuscan bank via PLT Holding and a long-standing supporter of Monte dei Paschi di Siena’s CEO, Luigi Lovaglio, is also considering whether to accept the Ca’ de Sass offer. “If we are to accept the offer,” said Tortora in Verona on Thursday 5 November on the sidelines of a conference held as part of the Connexum event, organised by Alma Iura, “we will accept it.” “Incidentally,” continued the entrepreneur from Romagna, “we increased our stake in July this year; so, let’s say that if we were to accept the OPAS, we would be an investor holding 0.3 per cent of Banca Intesa Sanpaolo today; to be precise, 0.308 per cent, because for us it’s money. We have also drawn up a plan there covering bonuses and dividends, which were announced just the day before yesterday by the chief executive of Banca Intesa Sanpaolo. We voted in favour on 29 October for the sake of consistency, because the board – representing the PLT list – had put forward a plan, and it seemed incredible to me to vote any other way, even though I knew that, essentially, the die had been cast by 29 October. Now – as Tortora was keen to emphasise – we are awaiting the information document, which I hope will be published on 10 November. As the announcements suggest, the Competition Authority is expected to give its ruling on that date, and we will study the documents. I can only reiterate today that we are patient investors and that we focus on the dividends paid out. It seems to me that Banca Intesa Sanpaolo’s dividend will be around 7 per cent in the coming years: a dividend that satisfies us. Tortora has therefore reiterated once again that ‘we are currently sitting on the sidelines, and if there is a need to participate, we will do so as medium- to long-term investors in any case. We are not speculators. This is an important message. I repeat, we must read and examine the information document and the Antitrust Authority’s findings, as the next steps are not yet a foregone conclusion. Not least because both Dr Lovaglio’s moves and those of Banca Intesa Sanpaolo were essentially carried out using assets belonging to the MPS shareholder. It is not as though they were carried out using third-party assets, because – as Tortora concluded – on the one hand the bank branches were sold, and on the other hand shares in Generali were sold to launch the takeover bid for Banca Generali.”
The non-performing loans sector
During the conference organised by Almaiura, it also emerged that artificial intelligence (AI) is playing an increasingly significant role in the future of the non-performing loans (NPEs). Although the benefits achieved to date are still limited, over 80 per cent of operators expect AI to have a positive impact on profit margins over the next 18–24 months. And that’s not all. Following the pressure on margins recorded in 2024, 2025 marks a recovery in profit margins for the Italian credit servicing sector (those who recover debts), driven primarily by improvements in operational efficiency. These findings emerge from EY’s analysis of data from the second edition of the Italian Study on Non-Performing Exposures (Sinpe 2026, also presented on Thursday 5 November at the Connexum conference, organised by Alma Iura), representing approximately 85 per cent of the Italian market for credit servicing in terms of assets under management.
The operational front
In 2025, the ratio of operating costs to total collections fell by 0.5 percentage points compared with the previous year, whilst the ratio of operating costs to revenue fell by 0.8 points. Ebitda per loan manager continued its upward trend, reaching approximately 100,000 euros, whilst the number of cases per loan manager in the portfolio continued to rise, with the sole exception of large-ticket loans (over 5 million).
Recovery performance also paints a picture that is constantly evolving. Exposures classified as Unlikely to Pay (UTP) – that is, loans for which full repayment is deemed unlikely without recourse to debt restructuring and/or the enforcement of guarantees – are showing a recovery in both the corporate and retail segments. For impaired loans classified as non-performing loans (NPLs), however, there has been substantial stability in the retail sector and a slight decline in the corporate sector, with the positive exception of exposures backed by public guarantees (MCC and SACE). “The recovery in profit margins,” commented Michele Thea, Europe West NPE Leader at EY-Parthenon, “indicates that the sector has responded to the pressures of 2024 by streamlining its operational processes. The next driver will be artificial intelligence: investment is currently focused primarily on process efficiency and credit management and assessment activities, whilst attention to customer relations remains limited. It is this transformation of the operating model that will play a key role in the sector’s evolution.”
Credit servicers turn their attention to private credit
The Italian servicer industry has therefore coped with the decline in non-performing loans from banks whilst safeguarding its profit margins, and is now expanding its scope to the broader field of high-risk credit in search of new areas of operation. ‘The market’s response,’ emphasised Giovanni Gilli, chair of the Connexum Scientific Committee, and Marco Rossi, chair of the Alma Iura Scientific Committee, ‘follows two strands of structural change: efficiency driven by technology, which is leading to substantial progress in the design of the business model for traditional activities; the effort to broaden the scope of operations, putting the expertise gained at the service of new and more complex asset classes. And in this regard, the broadening of the firm’s identity – in terms of both subject matter and audience – from pure NPEs to the wider world of high-risk credit is well justified.”


