
Road haulage: funds released – the race against time begins to claim reimbursements for price rises
By Resolution 40/E, the Italian Revenue Agency has introduced tax code 7082 to allow for the offsetting, via the F24 form, of the diesel tax credit accrued between March and August by 31 December

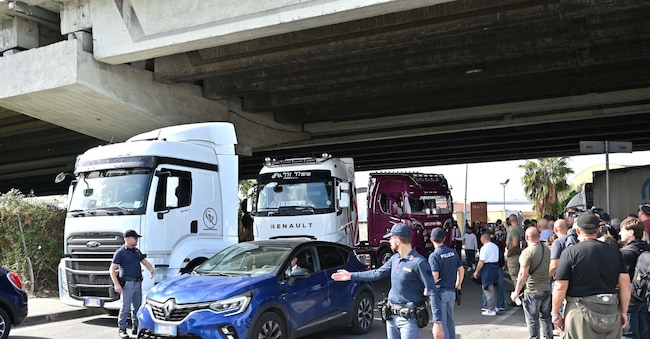
Whilst talks continue between the government – in particular Transport Minister Matteo Salvini – and road haulage associations, the Revenue Agency has launched the process for refunds to offset the high cost of diesel.
After days of waiting, Resolution No. 40/E has introduced tax code ‘7082’, which allows businesses to claim the extraordinary tax credit on the increased diesel costs incurred between March and August 2026 via the F24 form. Discussions with the sector began with a meeting a week ago at the Prefecture in Milan and are continuing at this very moment at the Ministry of Infrastructure and Transport (MIT), in a round-table meeting that Salvini himself has described as the forum for verifying the start of payments.
The tax credit
The tax credit, which has now reached 480 million following a number of government measures, covers up to 70 per cent of the increased expenditure on diesel compared with February’s prices. It is reserved for companies registered in the National Electronic Register of Road Haulage with Euro 5 and Euro 6 vehicles, a scheme subsequently extended to include the hire of buses with drivers. Applications are submitted via the platform set up by the Customs Agency and managed by Sogei.
The operational phase
We now move on to the operational phase. The credit may be used ‘exclusively for offsetting’ by 31 December 2026, by submitting the F24 form solely via the Revenue Agency’s online services, ‘failing which the payment will be rejected’. Each beneficiary can check their tax account to see the available amount notified by the MIT, which must not be exceeded.
Code 7082 must be entered in the ‘Tax Authorities’ section, in the column for offset credit amounts. If the company is required to repay the relief, it should instead be entered in the column for debit amounts paid. The ‘reference year’ field must show the year in which the expenditure was incurred. During processing, the Agency will verify that the taxpayer appears on the list of beneficiaries submitted by the Ministry and that the offset remains within the allocated limits, taking into account any subsequent changes or revocations. Otherwise, the F24 form will be rejected.

